All Categories
Featured
Choosing Professional Debt Management Services in 2026

Comparing Top Debt Consolidation Reviews Available Now

Best Financial Management Services for Households
Table of Contents
Government financial obligation relief programs don't cover all types of debt, but there are other options that can assist. Here's what you can do if you have debt issues the federal government can't solve.
These organizations include private financial obligation relief business and not-for-profit credit therapists. Here are a few of the services they may offer: Hardship programs: Lots of financial institutions offer challenge programs to help you get through difficult times. These programs might decrease or stop briefly payments, lower interest rates, or waive costs for individuals experiencing monetary problem.
Building a Robust Debt Plan LocallyThis could result in significant financial obligation decrease. Credit counseling: A licensed credit therapist can assist you produce a budget plan and find out money management abilities if you register in their debt management program.
Millions of Americans are having a hard time with charge card financial obligation, and in 2026, some might receive relief through charge card financial obligation forgiveness programs. These efforts, offered by major charge card issuers and financial organizations, are developed to help eligible customers minimize or eliminate impressive balances under particular conditions. Eligibility for credit card financial obligation forgiveness normally depends on numerous essential factors:: Individuals experiencing substantial financial obstacles, such as task loss, medical emergencies, or unanticipated household expenditures, might qualify.
Building a Robust Debt Plan Locally
Lenders may provide a settlement where a portion of the financial obligation is forgiven in exchange for a lump-sum payment or a structured repayment plan.: Some programs require proactive engagement with the credit card provider. Customers may work with a monetary counselor or directly with the financial institution to work out a settlement quantity that is lower than the total balance owed.
How to Reduce Unsecured Debt in 2026
This typically requires cautious budgeting to make sure the settlement can be satisfied completely.-: Structured payment programs coordinated by credit counseling companies might consist of forgiveness stipulations if the consumer successfully finishes the intend on time.-: Some issuers use momentary reductions in rates of interest, waived charges, or partial debt forgiveness to account holders experiencing monetary challenge.
Financial specialists recommend that anyone considering credit card financial obligation forgiveness first evaluate their financial situation, interact directly with their lender or a trusted counseling service, and understand both the short-term and long-term repercussions. With cautious planning and confirmation, qualified Americans can benefit from these programs in 2026 to lower financial stress and pursue long-lasting monetary stability.
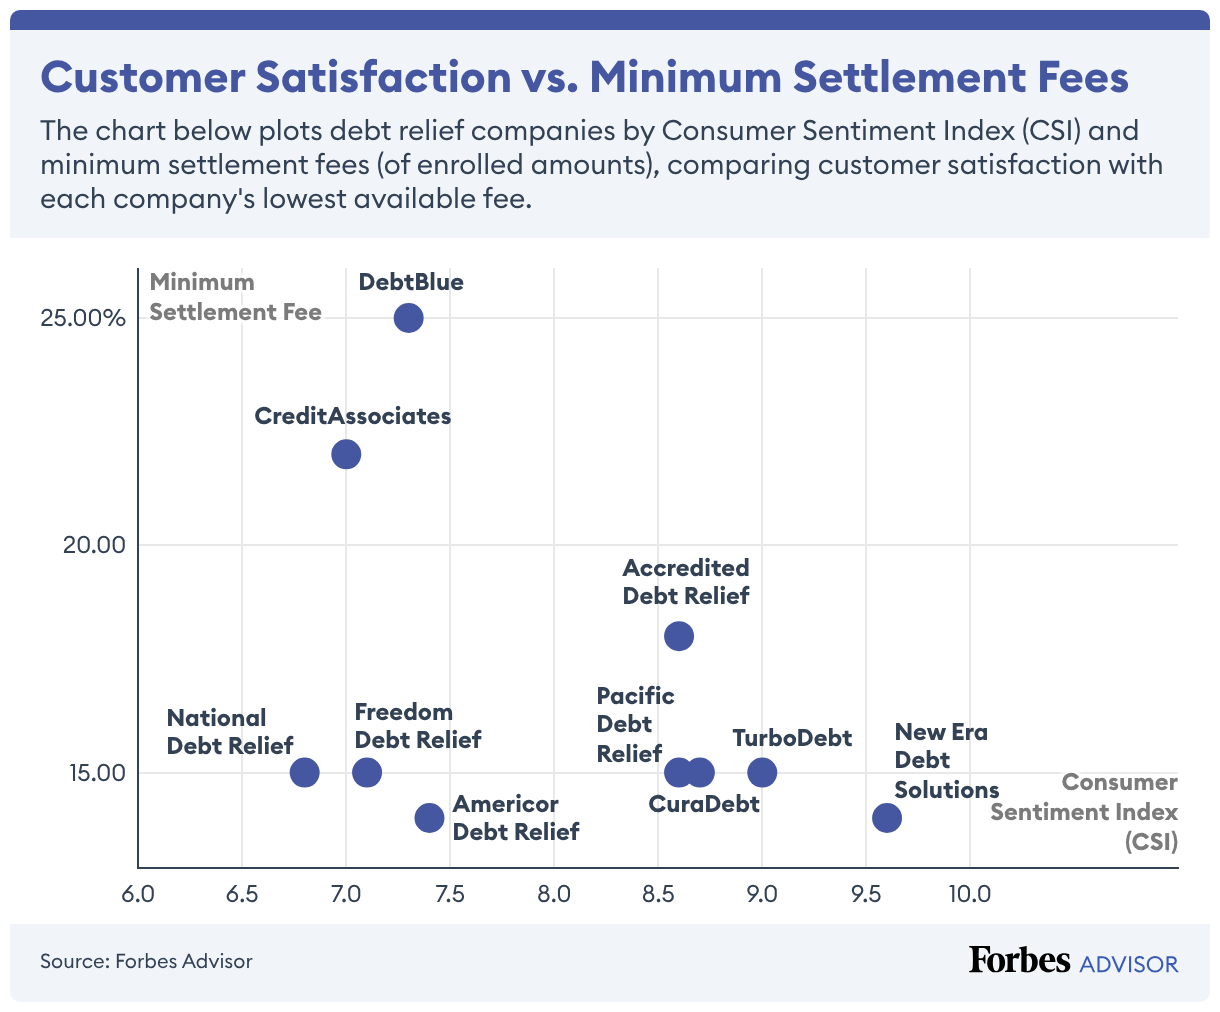
You have actually seen the advertisements guaranteeing to cut your debt in half. You've checked out Reddit cautions about business that charge upfront fees and vanish. Here are the genuine financial obligation relief programs that rank highestand how to decide in between settlement and credit therapy. Not all financial obligation relief programs fit all scenarios. Here's how to tell which one matches your difficulty level: Financial obligation combination loanNonePay 100%, much better termsGood credit, steady earnings, just require to simplifyCredit therapy (DMP)Mild/ModeratePay 100%, lower interestCurrent on payments, can afford lowered ratesDebt settlementSignificantPay less than 100%Currently behind, can't pay for minimumsBankruptcySevereLegal discharge/restructureOverwhelmed, creditors taking legal action against, no other option You're currently behind on payments by 90+ daysYou can't pay for minimum payments even with lower interestYou're dealing with substantial monetary difficulty (job loss, medical emergency, divorce)Your credit is currently harmed from missed out on paymentsYou can conserve $200-$500/month toward settlements You're present on payments or only a little behindYou have stable earnings to cover a regular monthly paymentYou wish to prevent significant credit damageYou can manage to pay back 100% if interest is loweredYou require 3-5 years to pay off debt Ask yourself: Can I afford my minimum payments if rates of interest were cut to 0-8%? Yes Credit therapy might workNo You likely need settlement or bankruptcyFor a total contrast of all financial obligation relief alternatives, see our debt relief programs guide.
Economists recommend that anyone considering charge card financial obligation forgiveness first evaluate their monetary scenario, interact directly with their lender or a trusted counseling service, and comprehend both the short-term and long-lasting repercussions. With mindful planning and verification, eligible Americans can benefit from these programs in 2026 to decrease monetary tension and pursue long-term financial stability.
Accessing Financial Hardship Help in 2026
Here are the legitimate debt relief programs that rank highestand how to choose between settlement and credit therapy. Not all financial obligation relief programs fit all circumstances. Here's how to tell which one matches your difficulty level: Financial obligation consolidation loanNonePay 100%, better termsGood credit, consistent earnings, just require to simplifyCredit therapy (DMP)Mild/ModeratePay 100%, lower interestCurrent on payments, can manage lowered ratesDebt settlementSignificantPay less than 100%Already behind, can't pay for minimumsBankruptcySevereLegal discharge/restructureOverwhelmed, creditors taking legal action against, no other choice You're currently behind on payments by 90+ daysYou can't pay for minimum payments even with lower interestYou're dealing with significant financial difficulty (task loss, medical emergency situation, divorce)Your credit is currently harmed from missed out on paymentsYou can conserve $200-$500/month towards settlements You're current on payments or just somewhat behindYou have steady earnings to cover a monthly paymentYou desire to prevent major credit damageYou can pay for to pay back 100% if interest is loweredYou require 3-5 years to pay off financial obligation Ask yourself: Can I manage my minimum payments if interest rates were cut to 0-8%?

Latest Posts
Choosing Professional Debt Management Services in 2026

How to Get 2026 Financial Hardship Relief
Reducing Unsecured Debt in 2026